Many people are worried about the mortgage rates being “high” in recent months.
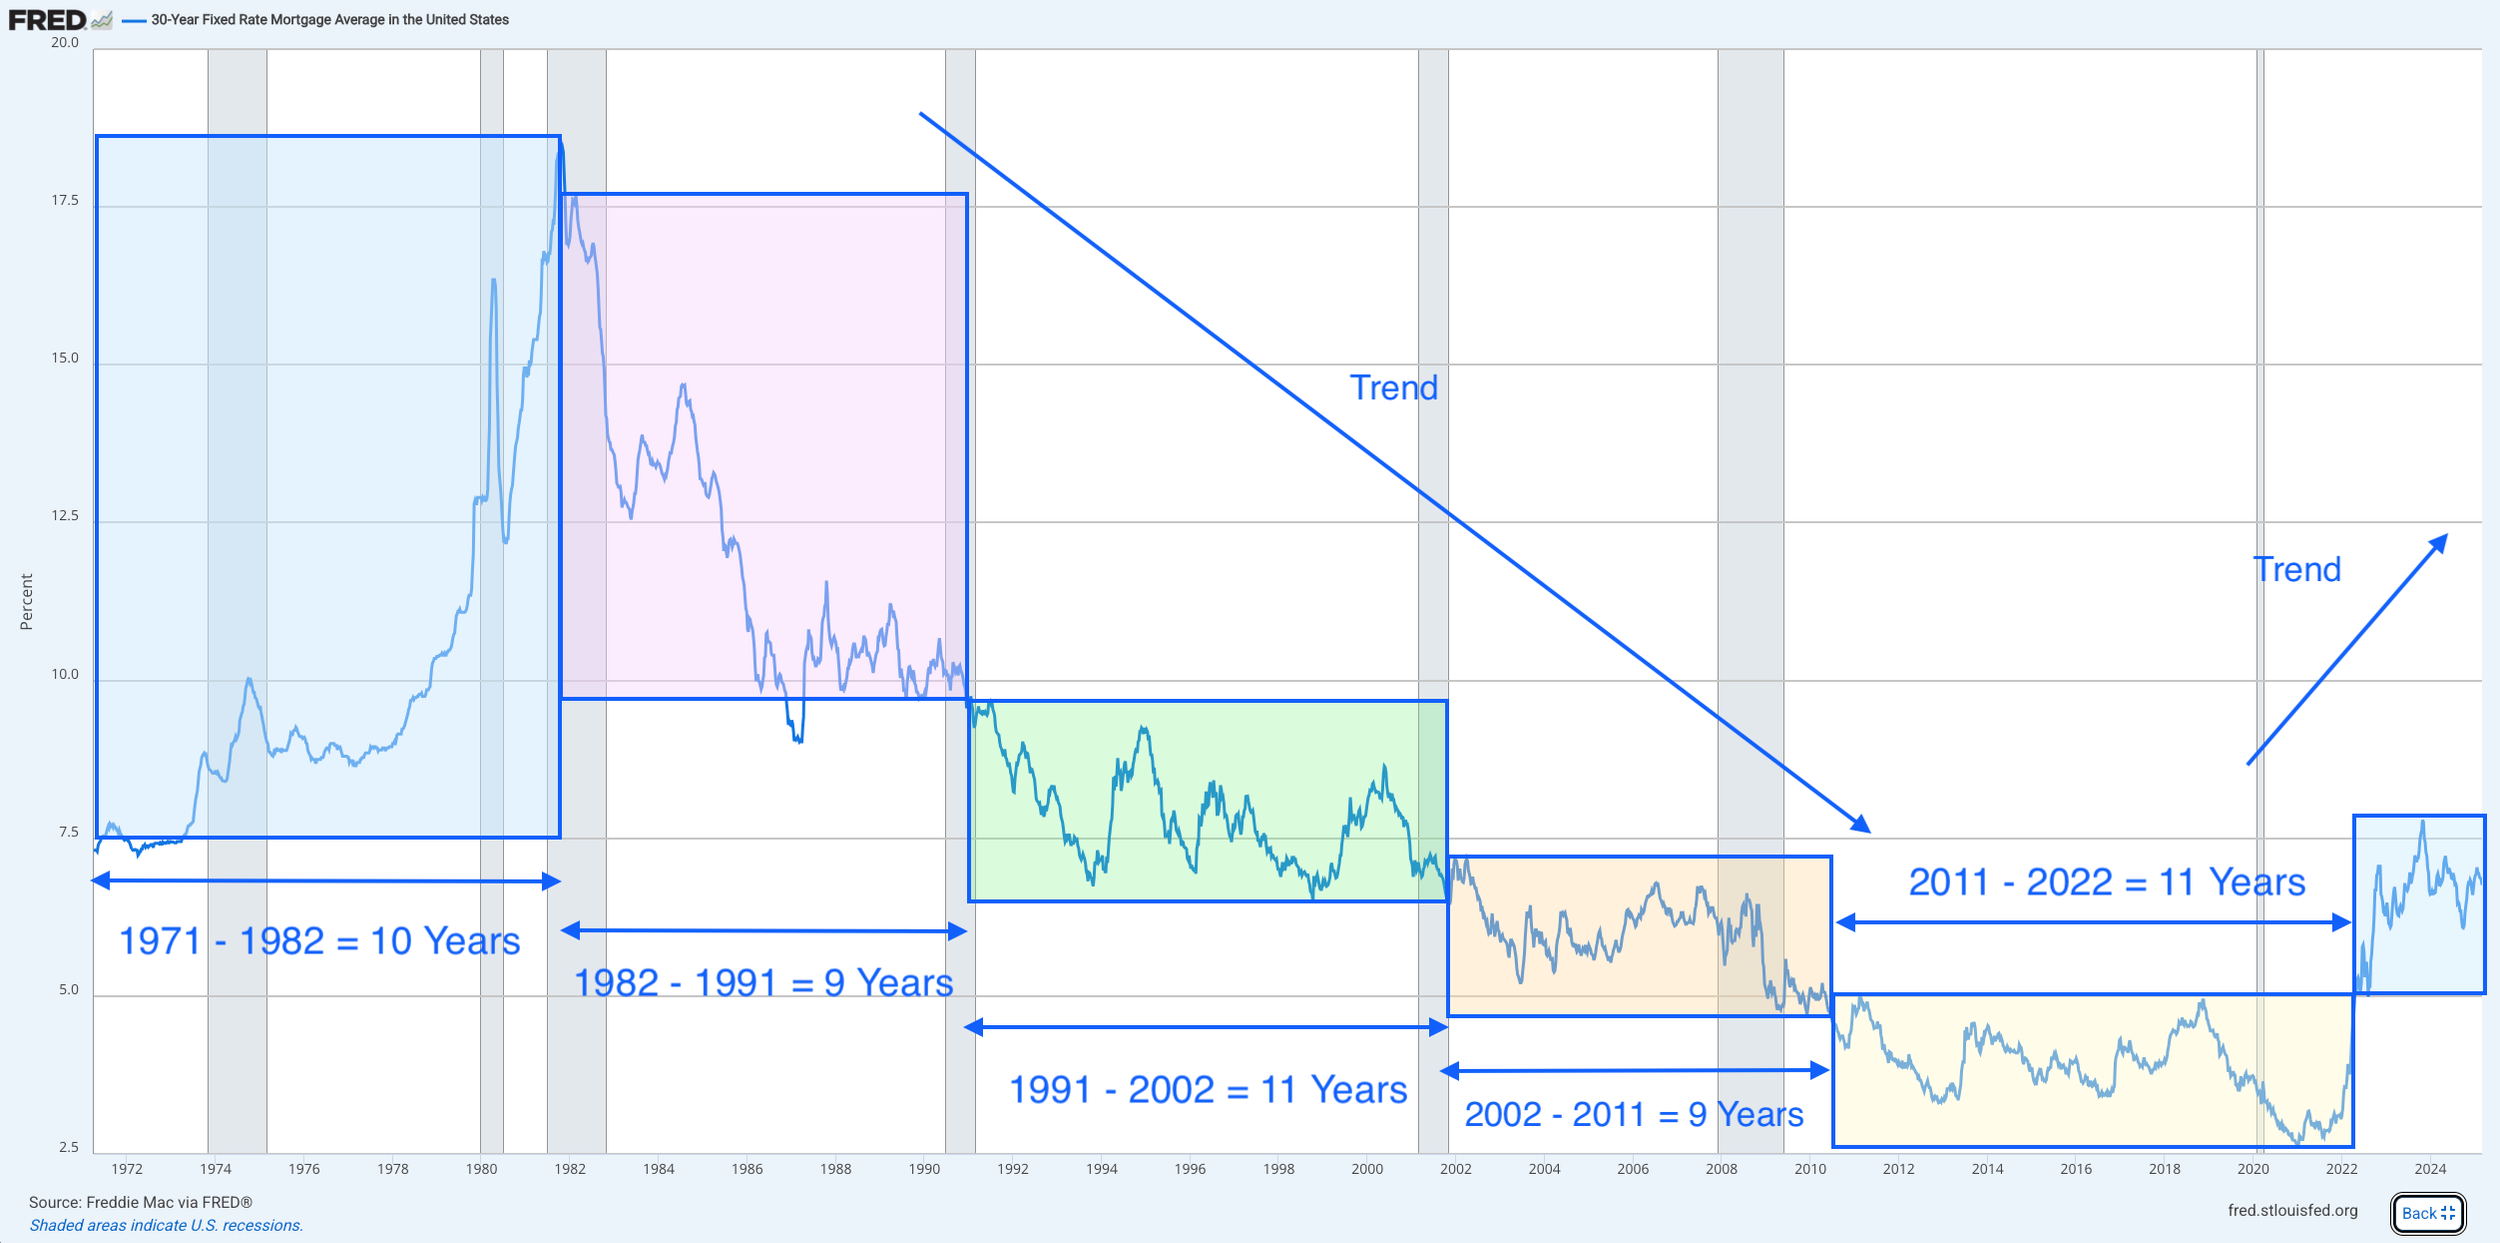
In reality, we are currently actually just a little below the historical average (comparing data since 1971).
To put things in perspective, here is some information about the historical mortgage rates, as well as a graph from the Federal Reserve Bank of St. Louis:
The 30-year fixed-rate mortgage average is 7.18% as of November 5, 2026, according to Freddie Mac.
Key Historical Milestones (30-Year Fixed)
All-Time Peak: Reached 18.63% in October 1981 (driven by Federal Reserve efforts to combat runaway inflation).
All-Time Low: Reached 2.65% in January 2021 (during the COVID-19 pandemic).
Historical Average: The long-term average since Freddie Mac began tracking in 1971 hovers around 7.69%.
Annual 30-Year Fixed Averages (Recent Decades)
Data compiled via Bankrate's Mortgage Rate History and FRED (Federal Reserve Economic Data):
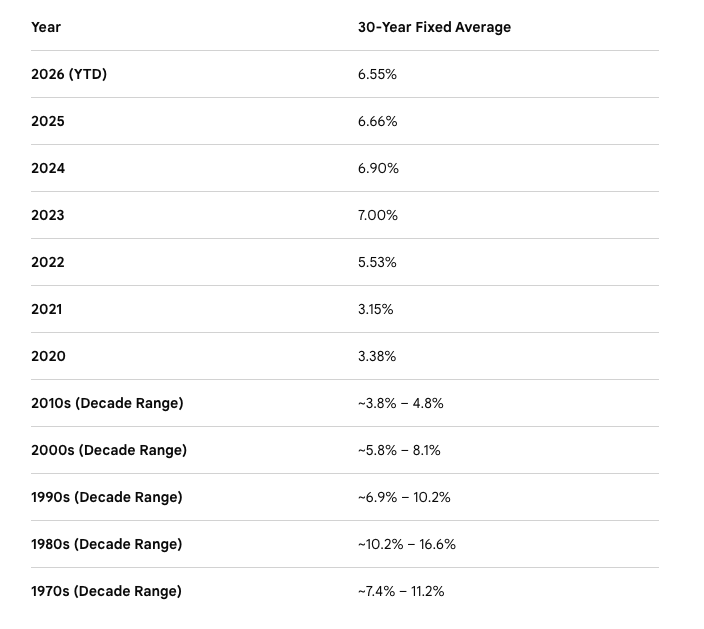
Because the current rates are higher than they were in 2020-2021, they look “high.” Some people are waiting to make their move until rates “go back down again.” Unfortunately, because of historical patterns, it could happen that mortgage rates will never go back down to the 2-3% within our own lifetimes.
For most people, the opportunity to buy a home only presents itself a few times in their life. What I mean by this is when all the factors align so that they are ABLE to buy a home and it makes sense with everything else in their lives to do so. Because these moments are few, I advise clients to base their decision on their own circumstances and what makes sense for them.
There is also the fact that, if you buy a home and rates go down later, then you could theoretically refinance. However, to err on the side of caution, I advise clients to go for a rate that they know they will be able to afford even if rates do not come down in the future.
Because everything in real estate is balanced, higher mortgage rates also means that property prices will have to come down. (If they wouldn’t, there would be no one left who can afford to buy said properties.) We have been seeing that starting to happen in the last few months, even in historically “hot” markets like Los Angeles.
If you are interested in discussing a specific scenario or getting some no-obligation advice on your personal real estate situation, please feel free to schedule a Free Brainstorming Consultation (usually around 45-50 minutes long). In addition to being a licensed mortgage broker in CA, FL, OR and TN, I am also a licensed and experienced California real estate broker, so I can provide answers to questions about selling, renting, holding, etc, on California properties.